Author’s photo. Bundi, Rajasthan
A fast start to the autumn: now rates have turned, how high do they go, energy markets, bloodlust, the old lessons, how stupid was the Afghan expedition? Taiwan Semi.
Hardly was my ink dry last week, when good-time girl Rayner threw out (“paused for review”) unitary authorities, in one of the fastest U turns I can recall. While I could barely believe the perfection of the Singapore political pay policy, in contrast. If you want top talent, pay top talent – this is as true in politics, as football or songwriting.
Step counters
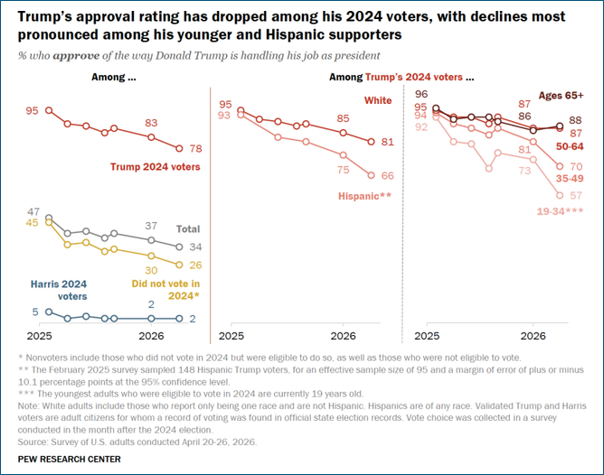
America has finally followed Europe in raising rates, so is this one and done? It depends if you see this as a new crisis, or a retreat from previous cuts. You can argue both, but the trauma last time was from a sudden switch to high inflation, and then a fairly laboured set of rate rises.
This time we are starting quite high, and it appears inflation, in particular services inflation, is not out of control. A sticky labour market has seen to that, jobs are not being shed rapidly, but nor are they being created, so little moves. Wage growth is still falling.
Is it all oily talk?
There is a lot of political talk: Macron, Merz both feeling like history, Trump set to be a lame duck, after the Mid Term elections, but the real impact of those is quite distant. Little Napoleons getting increasingly absurd, as they talk up war, while having no tools, and no money to pay for them.
We have argued that energy prices don’t matter now. It is notable that fiscal support for energy prices in the OECD, has been pretty nominal this time. Unlike during the Ukraine invasion, with politicians falling over themselves to throw money at the problem.
A harsh winter might shift that. Although oil matters little in domestic heating, and gas seems not to worry this government, or at least not enough to refill our storage caverns.
But the sense of systems, markets, flows, all adjusting to a steady price signal, remains strong. There is no energy panic.
We have just had the Reeves’ splurge of spending (did you notice) and are now entering the fiscal tightening years, to pay for it all. Expect that pain to be shifted deeper into the next Parliament now. The Bank has finally realised this is not a great time to unload long-dated Gilts either and is pausing that.
All in all, we do not need a set of upward steps. Not saying this inflation is transitory, but more that taking a sledgehammer to it, as yet, seems unlikely. For a while we have said 4%-5% is the target range. Markets of course got there months ago, (so actual commercial rates shifted a while back). Central Banks are quietly catching up.
More idiots
All too often we have gone blundering into someone else’s backyard, picked a fight, then retreated when they fought back. Credit goes to Burnham, for doing a great deal of talking, but committing very little in new resources to hard assets . As a good socialist, he knows it is futile.
How futile? Recently, Sergio Miller, author of “Pride And Fall”gave a talk about Blair’s Afghan nonsense. How ridiculously, callously, stupid we were to ever be involved – the author quoted chapter and verse on what was, in every way, a stunning British defeat, with good detail on how little the UK decision makers cared for either our troops or the Afghans. Amongst notional allies, the brave German forces were not allowed out after dark, and the Italians so committed, that they organised sky diving to alleviate the boredom of not bothering to fight. Orders came in, and they simply spiked them.
It was explained to the media as rational, yet it has taken decades for clarity to emerge, and no one has paid the price. Nor incredibly, so far, have we reformed the system that let it all happen.
And here we go again, thumping our chests, sounding alarms about mysterious threats, picking fights. Burnham would do well to look at Mr. Miller’s book, and then sit down to imagine writing the same, as he sticks our unwelcome nose into other’s affairs, once more.
I do not doubt there are votes in belligerence and jobs in munitions, but is our global ambition commensurate with our resources? If not, it is time to dial it down.
Another dangerous, narrow strait
What of Taiwan Semi (TSMC), some interesting comments by a company representative this week. The chip end of it is probably in a super cycle, but cyclical it still is. As fabricators, they can’t tell if their product is being well used, but they are rather more confident it will be used. But cautious about both volumes and financing.
There’s a great deal of uncertainty about who will actually profit from the AI bubble. Returns and investment are not well correlated in technology booms – neither predictable nor transparent, until history strips it all down and time reveals the winner.
Taiwan chip foundries are simply too big to move, their ecosystem too complex to replicate, and too reliant on global supply chains to be cut off. That may not make them safe, but nor can they be moved (in ownership or location) without destroying them.
In portfolio terms, this all keeps me on the cautious side, selling if prices firm. Equity markets cannot overcome rising rates, so as dividend yields drop and interest rises, history says we always switch from high risk, to lower. It may take a year or more, but as interest eats earnings, uncovering dividends, and deposit rates rise, we ultimately move.
Which is why the number of steps matters: a few, we can absorb, half a dozen, we can’t.
While I expect a few, do I want the risk of many?
The traditional destroyers, recession, mass layoffs, credit defaults, liquidity crunches, all appear far off. Corporate spreads are not shifting out; speculative liquidity still seems abundant, if likely reduced, from earlier this year.
There are still signs; the Turkish market the latest to see ill-informed retail inflows, seep into the soft sand of corruption.